Press & Media
Banks have spent a decade buying agile and getting ceremony instead. Standups, story points, quarterly planning theatre, a coach in every department, and delivery cycles that still move at the pace of the annual budget. David Fapohunda, who works in delivery within financial services, argues that most of what institutions call agile transformation never touched the element that determines speed: who owns the outcome and where the money sits. That distinction is about to get too expensive to ignore, because AI is dismantling the assumption agile was built on. Sprints exist to coordinate humans. When a coding agent produces a credible first pass in minutes, coordination stops being the bottleneck and governance replaces it.
Read
A bank’s contact center is a monument to problems that reached the customer. Every seat, script, and carefully tuned handle-time target exists because something went wrong upstream and nobody caught it. David Fapohunda has spent more than 25 years leading operations, AI enablement, and digital transformation across global banking platforms carrying millions of interactions, and he says the industry has spent decades perfecting the machinery of response while leaving the upstream failure largely untouched.
Read
As AI transforms financial services, the definition of customer-first is shifting from faster transactions to deeper understanding, greater transparency, and more meaningful human engagement. This article explores how financial institutions can use AI to strengthen empathy rather than replace it, while balancing hyper-personalisation with customer choice, trust, and governance. It also examines the leadership capabilities and workforce skills required to thrive in an AI-enabled future.
Read
Under Europe’s Digital Operational Resilience Act, a bank now has roughly 72 hours to report a major incident. That single regulatory clock has quietly rewritten the economics of how financial institutions operate. You cannot reconstruct the truth of what happened inside your operation that fast if your operating model was built to obscure it. Transparency has stopped being a virtue that leaders aspire to and become infrastructure they are legally required to demonstrate.
Read
In 2026, new DORA supervisory findings from the European Banking Authority revealed critical gaps in cloud resilience across regulated financial institutions, particularly around documentation, recovery testing, and hyperscaler concentration risk. This article examines why cloud migration programs often fail at the governance and framing stage, and how regulatory expectations are reshaping what “resilience” truly means in modern financial infrastructure.
Read
The era of AI governance living comfortably in the management layer is over. For years, boards were briefed, questions were asked, and executives returned to their teams to figure it out. That arrangement has collapsed. In the space of a few months, the conversation has shifted from whether boards should engage with AI to: how, how often, and with what level of personal accountability attached to the answer.
Read
Contact centers in financial services are emerging as a major governance and cost liability, with regulatory enforcement increasingly tied to unresolved customer journeys rather than isolated service metrics. This article explores why technology-first transformation efforts often fail, and how restructuring operations around customer journeys, repeat contact rates, and governance-first AI deployment leads to significantly stronger outcomes in both efficiency and customer experience.
Read
Modern fraud is increasingly adaptive and AI-driven, forcing financial institutions into a real-time arms race where speed, data quality, and infrastructure determine defensive capability. This article explores how unified data pipelines, human-informed AI systems, and scalable cloud-native architectures work together to improve fraud detection accuracy, reduce false positives, and enable institutions to prevent threats before they materialise.
Read
As financial institutions accelerate AI adoption, leadership effectiveness is emerging as a critical factor in successful transformation. This article explores how servant leadership principles can guide organisations through AI-driven change by strengthening clarity, trust, and shared purpose. It examines how leaders can empower teams to transition into oversight-focused roles, establish intent-driven autonomy, and embed trust as a core operational behaviour within AI-enabled systems.
Read
Many financial institutions still treat operational efficiency and customer experience as competing priorities, but modern transformation efforts show they are increasingly interdependent. This article explores how shifting from functional hierarchies to customer journey–based operating models, supported by unified data and simplified processes, enables organisations to reduce friction, improve scalability, and deliver stronger customer outcomes. It also examines how AI is expected to augment rather than replace operational roles in the near term.
Read
Despite significant investment in digital transformation, financial institutions often fail to achieve proportional productivity gains due to misalignment between technology initiatives and business outcomes. This article explores how embedding risk, governance, and cross-functional collaboration into transformation programs from the outset enables organisations to deliver measurable value. It also highlights the importance of aligning people, process, and data to ensure sustainable and scalable change in highly regulated environments.
Read
Fraud in financial services is becoming increasingly digital, automated, and complex, driven by advances in AI, synthetic identity creation, and faster payment systems. This report outlines key emerging risks including account takeover, internal fraud, and cross-account exploitation, while highlighting how regulatory developments such as GDPR, PSD2, and evolving authentication standards are reshaping fraud risk management strategies. It emphasises the need for integrated, agile operating models that combine fraud detection, cybersecurity, and real-time analytics.
Read
Account takeover (ATO) remains a persistent and costly challenge across financial services and payments, despite significant advances in fraud prevention technologies. This webinar explores why ATO continues to rise, examining current industry challenges, transformation-led fraud management approaches, and the role of behavioural biometrics and machine learning in strengthening authentication and reducing fraud losses.
Read
As data breaches continue to expose large volumes of personal information, financial institutions are increasingly adopting advanced authentication methods to prevent account takeover and strengthen identity verification. This session examines the limitations of siloed, cross-channel authentication strategies and explores how omni-channel authentication orchestration and risk-based approaches can unify fraud prevention, improve security, and enhance customer protection.
Read
As instant payments continue to reshape the financial services landscape, fraud risk is accelerating across registration, authentication, and transaction layers in real time. This webinar series explores the unique challenges of fraud in faster payment environments, highlighting how financial institutions must balance customer experience with robust, network-aware fraud controls. It also shares industry perspectives on real-time fraud prevention strategies and best practices for securing instant payment systems at scale.
ReadThis document outlines the agenda for a financial crime and fraud conference held in 2014, featuring industry speakers and sessions focused on payments security, fraud prevention, and regulatory trends in financial services.
Read
Event guide and presentation deck from the Payments 2014 conference held in Orlando, FL, covering industry sessions and agenda overview.
Read
At NACHA Payments 2014, financial institutions faced a dual reality of improving fraud detection capabilities alongside rapidly evolving and increasingly sophisticated threats. While advanced behavioural analytics were beginning to reduce fraud losses through anomaly detection, emerging risks such as compromised data aggregators, credential reuse, and mobile remote deposit capture (MRDC) fraud highlighted significant gaps in regulatory alignment and industry readiness. The discussion emphasised how fraud is becoming harder to detect as attackers leverage richer datasets and multi-account exploitation techniques.
ReadOn The News
As artificial intelligence becomes more capable of making decisions on its own, organizations face new challenges in managing and overseeing the technology. On the show, transformative AI leader and managing director David Fapohunda discussed why effective AI governance is becoming a critical responsibility for business leaders and corporate boards.
ViewSpeaking Engagements
David joins the CIOXNew York speaker line-up, listed as Managing Director, Operations Strategy, Transformation, Data Science & Analytics, and Delivery at Barclays.
View eventListed among the speakers for the Data Intelligence Summit NYC 2026.
View speakersRecognition
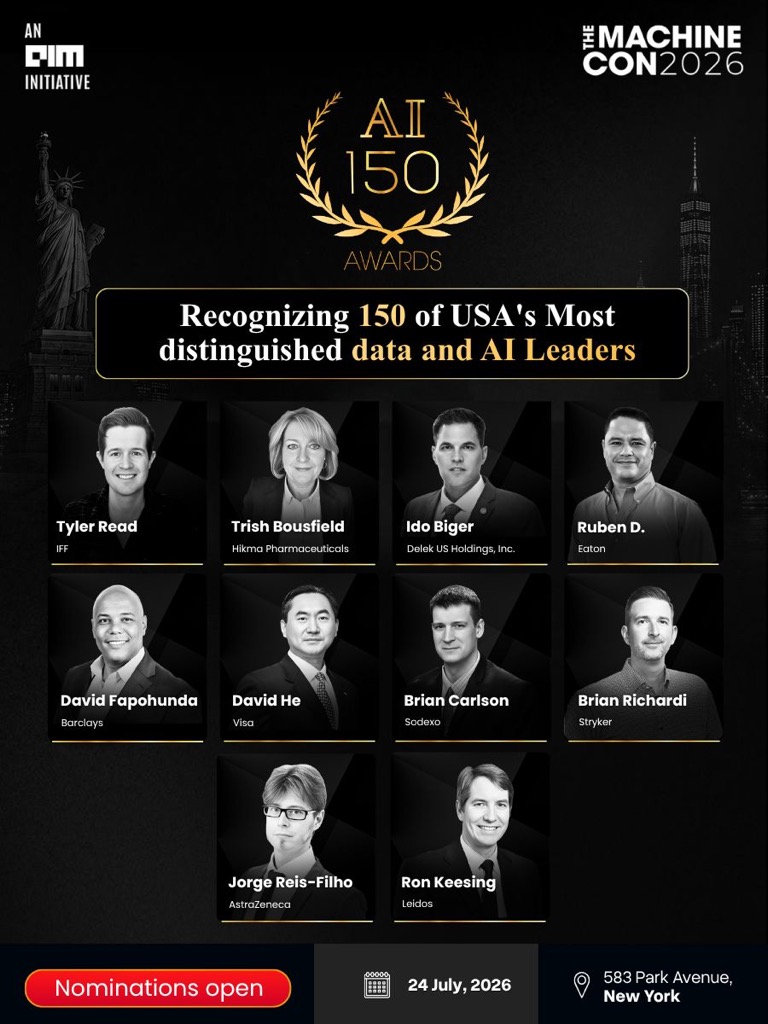
Featured among the data and AI leaders in the running for the AI150 Awards, which recognise 150 enterprise AI leaders in the United States.
View announcementVideos
Why are we still talking about ATO?
David Fapohunda discusses account takeover (ATO) fraud in financial services, explaining how fraudsters exploit identity data, digital channels, and weak authentication methods like OTPs. He emphasizes layered, adaptive security, better customer understanding, and industry collaboration to reduce fraud risk rather than attempting to eliminate it entirely.
Executive Statement | David Fapohunda - How Boardroom Expectations Around AI Governance is Evolving
David Fapohunda outlines how AI governance is rapidly becoming a board-level fiduciary responsibility, driven by regulatory expectations, investor scrutiny, and audit committee oversight. He emphasizes that boards must now demonstrate active, informed accountability for AI systems, as governance maturity increasingly impacts risk, valuation, and legal exposure.
CXO Dispatch | David Fapohunda - Boardroom Strategies for De-Risking Digital Transformation
David Fapohunda outlines four key strategies for de-risking digital transformation in financial services: aligning technology to clear business outcomes, embedding risk management from the start, prioritising people and operating model change, and using data as a unifying layer across silos. He emphasises that successful transformation requires balancing innovation with control, compliance, and human-centred execution.